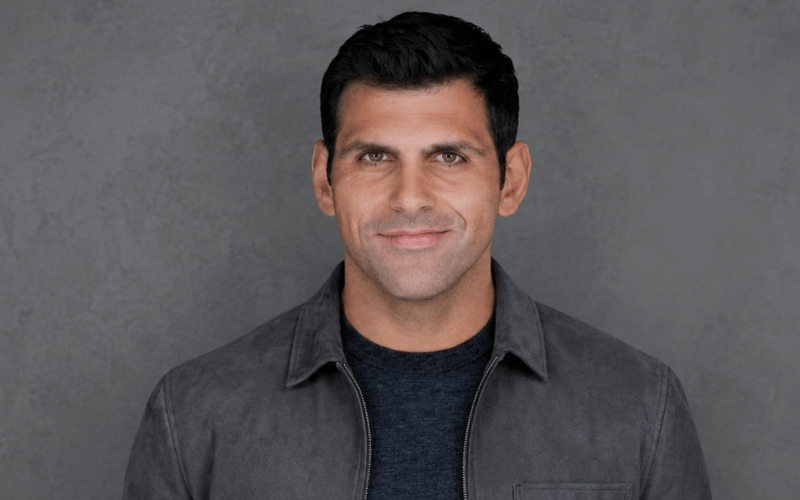
Joseph Martin, Founder and CEO of Kinectify, leads an AML risk management technology and advisory company serving regulated gaming operators, from tribal casinos to major commercial properties. Kinectify’s platform continuously assesses risk across entire customer populations, helping operators move beyond alert- and threshold-driven reviews toward genuinely risk-based AML programs.
In this CasinoRank interview, Martin discusses why AML has become a technology challenge rather than a staffing one, and why property-by-property monitoring often misses coordinated financial crime spanning multiple channels. He distinguishes compliance that looks good on paper from programs that demonstrate real effectiveness, touching on the industry’s false-positive problem. Martin also outlines where AI adds the most value in compliance work, why human judgment remains essential to final regulatory decisions, and why a connected, enterprise-wide intelligence layer is key to identifying financial crime as gaming ecosystems evolve.
Joseph, if AML programs are constrained by capacity rather than risk, what prevents operators from investigating more high-risk activity?
Joseph Martin: For years, the industry has viewed AML as primarily a staffing challenge. In reality, it has become a technology challenge. The volume of player activity, financial transactions, gameplay, public records, and other risk signals has grown far beyond what human investigators can evaluate on their own.
That creates a fundamental problem. You can’t investigate risks that you can’t see. Many operators still aren’t continuously assessing risk across their entire customer population. Instead, they investigate alerts, thresholds, or customers who happen to come to their attention. Those are important, but they don’t necessarily represent the highest-risk individuals within the business.
Designing AML Around Risk, Not Investigator Capacity
Joseph Martin: As customer populations and transaction volumes continue to grow, every compliance program eventually encounters the same constraint: human capacity. An investigator can only complete a finite number of reviews each year. As a result, many organizations unintentionally begin designing their AML programs around what their teams have time to review rather than where the greatest risks actually exist.
That’s the difference between a truly risk-based program and what I would call a capacity-based program. A risk-based program investigates where the risk is. A capacity-based program investigates what people have time to review.
Why Scaling AML Requires Continuous Risk Assessment
Joseph Martin: The industry won’t solve this challenge simply by hiring more investigators. The scale of modern gaming makes that approach unsustainable. Instead, operators need technology that continuously assesses risk across the entire customer population, enriches player activity with internal and external intelligence, and helps investigators focus their expertise on the highest-risk activity. Human judgment remains essential, but technology provides the visibility and scale necessary to deliver the kind of effective, risk-based AML programs that regulators increasingly expect.

If financial crime involves coordinated networks, how should operators identify it, and where do traditional monitoring systems fall short?
Joseph Martin: Financial crime rarely occurs in isolation. Whether it’s money laundering, fraud, structuring, or the use of third parties, illicit activity often involves coordinated networks spanning multiple individuals, accounts, businesses, and transactions. Which becomes challenging when many compliance programs are designed to investigate customers one case, one property, or one channel at a time.
Today’s gaming operators are no longer single-property businesses. Many operate portfolios that include multiple casino properties, online gaming, sports betting, digital wallets, and other player touchpoints. Yet compliance programs are often organized around those individual business units with separate teams, monitoring processes and investigations. That makes it difficult to develop a complete understanding of customer risk across the enterprise.
Why Property-by-Property Monitoring Misses Connected Risk
Joseph Martin: Increasingly, regulators expect operators to understand how customers interact across their entire business, not just within a single property or channel. A player may appear relatively low risk when viewed in isolation, but their activity across multiple properties, gaming channels, payment methods, or connected individuals may tell a very different story. Without an enterprise-wide view, those patterns can easily go undetected.
The industry needs to move beyond asking, “Is this customer high risk at this property?” and begin asking, “What is the overall risk of this customer across our organization, and who are they connected to?” Technology makes that possible by bringing together player activity, transactional data, customer intelligence, and relationship analysis into a unified view that would be nearly impossible to assemble manually.
Ultimately, the goal isn’t simply to produce more alerts. It’s to provide investigators with the complete context they need to identify coordinated activity, understand enterprise-wide customer risk, and deliver higher-quality investigations and more meaningful suspicious activity reports.
Regulators increasingly expect AML programs to demonstrate effectiveness, not just compliance on paper. What separates a mature program from one that only appears robust during an audit?
Joseph Martin: For many years, compliance programs were largely evaluated based on whether they had the right policies, procedures, training, and documentation in place. Those remain important, but regulators are increasingly asking a more fundamental question: Is your AML program actually effective at identifying, investigating, and reporting financial crime?
From Compliance on Paper to Real Effectiveness
Joseph Martin: A mature compliance program doesn’t measure success by the number of alerts it generates or the number of cases it closes. It measures success by how effectively it identifies meaningful risk, how consistently it prioritizes investigative resources, and whether it can demonstrate that high-risk activity is being identified and addressed across the organization.
One of the clearest indicators of program effectiveness is the quality of its alerts. Across the industry, we’ve seen organizations operating with false-positive rates of 95 to 99 percent, particularly when they rely on legacy monitoring platforms, systems designed by gaming machine manufacturers, tools built in-house, or systems that weren’t purpose-built for gaming. This high false alert rate means the overwhelming majority of investigative effort is spent reviewing activity that isn’t ultimately suspicious.
The False-Positive Problem Is Consuming Investigative Capacity
Joseph Martin: Beyond creating unnecessary friction for legitimate players, it diverts valuable investigative resources away from identifying genuine financial crime.
The most mature organizations recognize that effectiveness isn’t about generating more alerts. It’s about generating better alerts. Technology should help investigators focus on the small percentage of activity that truly warrants review, allowing experienced professionals to spend their time applying judgment where it matters most.
The most mature organizations also embrace continuous improvement. They regularly evaluate whether their monitoring strategies, risk models, and investigative processes are producing meaningful outcomes, and they adapt as criminal methodologies, player behavior, and regulatory expectations evolve.
Ultimately, the difference between compliance and effectiveness is simple. Compliance demonstrates that you followed your process. Effectiveness demonstrates that your process actually works.
AI is becoming a larger part of compliance investigations. Where does it deliver the most value today, and which decisions still require experienced human judgment?
Joseph Martin: AI is transforming compliance because it’s exceptionally good at the work that has historically consumed most AML departments. Much of the day-to-day effort isn’t investigative analysis. It’s gathering information, reviewing transactions, researching public records, screening watchlists, documenting findings, completing forms, and preparing case files. Those activities are essential, but they’re also repetitive, data-intensive, and highly structured, making them ideal for AI.
Moving Investigators From Data Collection to Risk Analysis
Joseph Martin: When those tasks become largely automated, compliance teams can fundamentally change how they operate. Instead of spending the majority of their time collecting and organizing information, they can focus on understanding risk, identifying complex financial crime, and making well-supported regulatory decisions. That’s where the real opportunity lies. AI doesn’t just make existing processes faster. It allows organizations to rethink how AML work is performed altogether.
AI is also accelerating innovation within the compliance technology industry itself. As criminal methodologies and regulatory expectations evolve, software providers need to respond much more quickly than they could in the past. AI is dramatically reducing development timelines, allowing new capabilities, risk models, and investigative workflows to be delivered in months rather than years. That means operators can adapt more quickly as financial crime continues to evolve.
There are still decisions that require experienced human judgment. Determining whether activity is genuinely suspicious, evaluating context that may not be evident in the data, and deciding whether to file a Suspicious Activity Report remain matters of professional judgment and accountability. AI can assemble the facts, identify patterns, and present evidence remarkably well. Experienced investigators are still responsible for making the final regulatory decisions.
Ultimately, the greatest promise of AI isn’t that it helps investigators work a little faster. It’s that it fundamentally changes the economics and scalability of AML, allowing compliance programs to analyze more activity, identify more meaningful risk, and adapt more quickly than ever before.
Kinectify works with regulated gaming operators from tribal casinos to major commercial properties. What compliance challenges are most common across these environments, and what consistently surprises operators?
Joseph Martin: One of the things that has surprised us most is how similar the challenges are across jurisdictions. Whether we’re working with tribal casinos, large commercial operators, or clubs in Australia, the underlying problems are remarkably consistent. Compliance teams everywhere are struggling with growing data volumes, fragmented systems, increasing regulatory expectations, and the challenge of understanding customer risk across an entire player population rather than through isolated investigations.
We’re also seeing a convergence in regulatory expectations. While each jurisdiction has its own regulatory framework, the direction is remarkably similar. Regulators increasingly expect operators to leverage transaction monitoring, risk scoring, pattern recognition, and enterprise-wide visibility to support genuinely risk-based AML programs. Those expectations simply become more difficult to achieve as customer populations and transaction volumes continue to grow using traditional manual processes alone.
Another challenge that consistently surprises operators is the level of variation in investigative decision-making. We’ve seen situations where multiple experienced analysts review substantially similar activity and reach different conclusions about whether it warrants escalation or a Suspicious Activity Report. That inconsistency becomes even more pronounced across large organizations operating dozens of properties, where different teams may develop different interpretations of the same corporate policies and risk appetite.
Technology helps create consistency without eliminating professional judgment. It provides standardized risk models, consistent investigative workflows, and the analytics needed to understand how decisions are being made across the organization. Experienced investigators still make the final determination, but management gains much greater visibility into whether similar risks are being treated consistently across the enterprise. Ultimately, that leads to stronger governance, more defensible decision-making, and a more mature compliance program.
As payment methods and player ecosystems evolve, which emerging financial crime trends should casino operators watch most closely over the next few years?
Joseph Martin: New payment methods, digital wallets, online gaming, sports betting, and increasingly connected player ecosystems are all changing how customers interact with gaming operators. While each innovation creates new opportunities, they also generate more data, more transactions, and more ways for financial crime to move across an organization.
The Bigger Risk Is Fragmentation Across the Player Journey
Joseph Martin: The greatest challenge over the next few years will not be any single payment method or criminal typology. I believe developing a holistic understanding of customer behavior across all of those channels will become the greater challenge. A player no longer interacts with an operator through a single property or a single payment mechanism. They move seamlessly across physical casinos, online platforms, sports betting, loyalty programs, and multiple funding methods. Compliance programs need to be just as connected.
That requires a horizontal intelligence layer across the enterprise. Rather than evaluating risk separately within each property, product or payment channel, operators need the ability to continuously aggregate and analyze customer activity across their entire organization. Only then can they develop a complete understanding of player behavior, identify suspicious patterns that span multiple channels, and make truly risk-based decisions.
Ultimately, the future of AML isn’t about monitoring more systems independently. It’s about connecting those systems so investigators have a single, enterprise-wide view of customer risk. As gaming ecosystems become more interconnected, the operators with the strongest intelligence layer across their businesses will be best positioned to identify emerging financial crime and adapt to whatever comes next.
You’ve spoken about greater collaboration in financial crime prevention. How realistic is information sharing between operators and regulators, and what would make it effective and practical?
Joseph Martin: Greater collaboration is not only realistic, but necessary. Financial crime doesn’t stop at the boundaries of a single property, operator, or jurisdiction. As gaming becomes increasingly interconnected, the industry’s ability to share meaningful intelligence will become just as important as its ability to monitor individual transactions.
We’ve made encouraging progress from a policy perspective. Regulators and industry leaders increasingly recognize the value of information sharing, and there are existing legal frameworks that support collaboration. The next challenge is operationalizing those concepts in a way that’s scalable, timely, and practical.
Turning Information Sharing Into Operational Intelligence
Joseph Martin: Today, much of that collaboration still relies on manual processes such as emails, phone calls, documents, and ad hoc requests. Those methods can certainly be effective in individual cases, but they don’t create a systematic, enterprise-wide intelligence capability. To truly strengthen financial crime prevention, the industry needs technology that allows information to be shared, analyzed, and acted upon in a structured and consistent way.
Looking ahead, I believe the opportunity extends beyond information sharing between organizations. Operators also need better intelligence sharing within their own enterprises. Many large gaming companies still manage AML independently across different properties, products, and business units. Building a horizontal intelligence layer that connects those environments is an important first step. Once organizations have a unified internal understanding of customer risk, broader collaboration among operators and regulators becomes significantly more practical and valuable.
Ultimately, I believe the future isn’t simply more information sharing. It’s better intelligence sharing. The organizations that can securely transform information into actionable intelligence, while maintaining appropriate privacy protections and regulatory safeguards, will be best positioned to combat increasingly sophisticated financial crime.
Final Thoughts
Martin’s perspective points to a clear shift in AML: the challenge is no longer simply handling more alerts, but building the intelligence needed to understand risk across the entire customer relationship. As gaming ecosystems become more connected, fragmented monitoring leaves too much room for coordinated activity to go unnoticed. The advantage will increasingly sit with operators that can connect data, reduce false positives, and give investigators the context to focus their judgment where it matters most.

With a background in digital media and a keen eye for emerging technologies, Ronaldo bridges the gap between players and platforms through clear, insightful reporting to the iGaming industry.